The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Professional indemnity and public liability insurance protect freelancers against different kinds of business risks. This guide explains how they differ, when each may respond, and what sole traders should check before comparing policies.
Professional indemnity and public liability insurance are two of the most common types of freelancer insurance in Australia, but they are often confused. Both can help protect a freelance business from claims, yet they respond to different events.
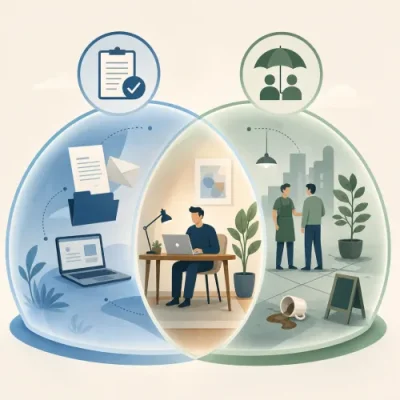
In simple terms, professional indemnity insurance is generally about claims arising from your professional advice, services, errors or alleged negligence. Public liability insurance is generally about claims involving injury to other people or damage to their property connected with your business activities.
This article explains the practical difference for freelancers and sole traders, including examples, contract considerations and questions to ask before seeking quotes. It is general information only and does not take your personal circumstances into account.
Professional indemnity vs public liability at a glance
| Feature | Professional indemnity insurance | Public liability insurance |
|---|
| Main risk it addresses | Claims that your professional advice, services, design, recommendation or work caused a client financial loss | Claims that your business activities caused injury to a third party or damage to third-party property |
| Common claim trigger | An alleged mistake, omission, breach of professional duty or negligent advice | A person is injured, or someone else's property is damaged, because of your business operations |
| Typical freelancer examples | A consultant's report contains an error that leads to a client loss; a designer's work allegedly fails to meet the agreed brief and causes financial harm | A client trips over your equipment during a site visit; you accidentally damage a client's laptop while working at their premises |
| Who usually claims? | Often a client or former client | Often a client, member of the public, venue owner, supplier or other third party |
| Key policy details to check | Professional services description, retroactive date, exclusions, claims-made conditions, limit of indemnity and excess | Business activities description, locations, product liability if relevant, exclusions, limit of indemnity and excess |
What professional indemnity insurance is designed to cover
Professional indemnity insurance is intended for claims connected with the professional services you provide. For freelancers, this may include advice, consulting, creative work, technical services, strategy, project management, design, writing, marketing, bookkeeping or other specialist work, depending on the policy and the occupation insured.
A professional indemnity claim may arise where a client alleges that your work, advice or failure to act caused them financial loss. The claim does not always need to be clearly valid for it to be stressful or expensive. Depending on the policy, professional indemnity insurance may help with legal defence costs and compensation or settlement amounts that are covered under the policy.
Common professional indemnity scenarios for freelancers may include:
- a client alleges that your advice was incorrect and caused them to lose money;
- a project deliverable contains an error that creates additional costs for the client;
- you are accused of breaching professional duty, confidentiality or a contractual obligation;
- a client claims your design, report, campaign, specification or recommendation was negligent;
- you are drawn into a dispute even though you believe you acted properly.
Professional indemnity policies are commonly written on a claims-made basis. This means the timing of when a claim is made and notified can be important, as can the policy's retroactive date. Freelancers should read these provisions carefully and ask the insurer or broker to explain anything unclear.
For a deeper guide to this cover type, see The Importance of Professional Indemnity Insurance for Freelance Work.
What public liability insurance is designed to cover
Public liability insurance is intended for claims involving third-party injury or third-party property damage connected with your business activities. It is not mainly concerned with whether your advice or professional work was correct. Instead, it focuses on physical injury or property damage.
For freelancers, public liability can be relevant if you meet clients in person, attend events, work at client sites, visit shared workspaces, hire venues, run workshops or interact with members of the public as part of your business.
Common public liability scenarios may include:
- a client trips over your bag, cable or equipment during a meeting;
- you accidentally spill liquid on a client's device while working at their office;
- your display materials or work setup damage a venue's floor or wall;
- a visitor is injured at a workshop or event you are running;
- your business activities cause damage to property owned by someone else.
Public liability policies differ in what they cover, how they define business activities, and whether product liability or other extensions are included. Freelancers who sell physical products, install equipment, work at markets or run events may need to check these details particularly carefully.
For more detail, read Understanding Public Liability Insurance: A Freelancer's Guide.
Why freelancers often confuse public liability and professional indemnity
The confusion usually comes from the fact that both policies can involve client claims and both are used by freelancers, contractors and sole traders. They may also appear together in client contract requirements or tender documents.
The easiest way to separate them is to ask what went wrong:
- Was the claim about professional advice, a service mistake or alleged negligence causing financial loss? Professional indemnity may be the relevant cover type.
- Was the claim about someone being injured or another person's property being damaged? Public liability may be the relevant cover type.
Some real-world situations can involve both legal and practical complexity. For example, a freelancer might attend a client's premises to deliver a project. If the client alleges the project advice caused a financial loss, that points towards professional indemnity. If the freelancer also damages the client's equipment during the visit, that points towards public liability. The same client relationship can create different types of risk.
Examples by freelance occupation
The right cover depends on the work you do, the contracts you sign and the risks attached to your services. The following examples are general only, but they show how the distinction can apply in practice.
Freelance web developer
A web developer may look to professional indemnity for allegations that a coding error, missed requirement or project advice caused the client financial loss. Public liability may be relevant if the developer visits a client's office and accidentally damages equipment or causes someone to trip over work gear.
Freelance marketing consultant
A marketing consultant may face professional indemnity risks if a client alleges that strategic advice, advertising material or campaign management caused financial harm. Public liability may be relevant if the consultant runs an in-person workshop and a participant is injured because of the event setup.
Freelance designer or creative professional
A designer may need to consider professional indemnity for disputes about design errors, missed specifications, alleged copyright-related issues or client losses linked to professional services, subject to the policy terms. Public liability may be relevant for studio visits, installations, exhibitions, photoshoots or client-site work where physical injury or property damage could occur.
Bookkeeper, consultant or business adviser
Freelancers who provide technical, financial, administrative or business advice may have professional indemnity exposure if a client alleges an error in the service caused financial loss. Public liability may still matter if they visit client premises, operate from a shared workspace or host clients at a business location.
Do freelancers need both types of insurance?
Some freelancers may need one, both or neither, depending on their occupation, clients, contracts, work locations and risk tolerance. There is no single answer for every sole trader.
You may be more likely to consider professional indemnity insurance if you:
- provide advice, consulting, design, strategy, technical services or specialist recommendations;
- create work clients rely on to make business decisions;
- handle sensitive client information or important deliverables;
- work under contracts that require professional indemnity cover;
- operate in an occupation where clients or professional bodies expect it.
You may be more likely to consider public liability insurance if you:
- meet clients, suppliers or members of the public in person;
- work at client premises, venues, markets, events or shared workspaces;
- use equipment, cables, displays, tools or materials around other people;
- host workshops, training sessions or in-person consultations;
- have contracts that require public liability cover.
Client requirements can be influential, but they should not be the only consideration. A contract may specify a minimum insurance limit, insured entity name or certificate of currency requirement. You still need to check whether the policy actually matches your occupation and activities.
What to check in client contracts and certificates of currency
Many freelancers first compare public liability and professional indemnity because a client contract asks for one or both. Before arranging cover, review the wording carefully. If you are unsure, seek clarification from the client, insurer or an appropriately qualified adviser.
Items to check may include:
- Type of insurance required: Does the contract ask for professional indemnity, public liability, product liability, workers compensation or another cover?
- Minimum limit: Does the client specify a particular limit of indemnity or public liability limit?
- Business name and insured entity: Does the policy need to be in your legal name, trading name, company name or ABN-linked entity?
- Occupation description: Does the policy accurately describe the work you perform?
- Geographic scope: Does the policy respond where you work and where your clients are based?
- Contractual liability exclusions: Does the policy exclude liabilities you accept under contract beyond normal legal liability?
- Retroactive date for professional indemnity: Does the policy cover past work, or only work after a certain date?
- Subcontractors: Are subcontractors covered, excluded or required to hold their own insurance?
If the contract language is unclear or your work is specialised, a broker may be able to help you discuss occupation-specific insurance options. You can use the site's Brokers page as a starting point for finding assistance, noting that availability, recommendations and policy outcomes depend on individual circumstances and provider criteria.
How pricing and policy terms may differ
Professional indemnity and public liability premiums are not calculated in exactly the same way. Insurers may consider different risk factors for each policy.
For professional indemnity, factors may include the type of professional service, annual revenue, contract values, qualifications, claims history, jurisdictions, policy limit, excess, retroactive date and whether the work involves higher-risk advice or regulated services.
For public liability, factors may include the nature of your business activities, whether you work from home, visit client premises, host events, use tools or equipment, sell products, employ staff or subcontractors, and the level of cover requested.
Price should not be assessed in isolation. A cheaper policy may have exclusions, limits or definitions that make it less suitable for a particular freelancer's risks. Conversely, a higher premium does not automatically mean a policy is appropriate. The wording, insured activities and exclusions matter.
Common misunderstandings to avoid
- "Public liability covers all client disputes." It generally does not cover disputes about the quality of your advice or professional work unless the policy wording says otherwise.
- "Professional indemnity covers physical accidents." It is generally designed for professional service claims, not third-party injury or property damage.
- "A client only needs a certificate, so the details do not matter." The certificate is only evidence of insurance. The policy terms determine what is covered.
- "Working from home removes public liability risk." It may reduce some exposures, but freelancers may still meet clients, attend events or work at other locations.
- "If I am a sole trader, my risks are too small to matter." Sole traders can still face claims, legal costs and contract insurance requirements.
Questions to ask before comparing policies
Before you request quotes, it can help to clarify the specific risks in your freelance business. Consider asking:
- What professional services do I provide, and how should they be described to an insurer?
- Could a client suffer financial loss if my work contains an error or omission?
- Do I visit client premises, attend events or interact with the public?
- Do my contracts require professional indemnity, public liability or both?
- What limits, excesses and exclusions apply?
- Does the professional indemnity policy cover prior work, and what is the retroactive date?
- Are subcontractors, collaborators or outsourced work included or excluded?
- How do I notify a circumstance that may later become a claim?
Keeping records of contracts, project scopes, approvals, client instructions and changes can also support good risk management. Insurance is one part of protecting a freelance business, alongside clear agreements, careful communication and professional processes.
The bottom line for freelancers
Professional indemnity and public liability insurance protect against different risks. Professional indemnity is generally focused on claims arising from your professional services, advice, errors or alleged negligence. Public liability is generally focused on third-party injury and property damage connected with your business activities.
Many freelancers compare both because clients may request them together, but they are not interchangeable. The most suitable approach depends on your work, contracts, locations, claims exposure and insurer criteria. Reading the policy wording and asking informed questions can help you compare freelancer insurance types more confidently.
Published: Sunday, 20th Sep 2026
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.